
PREMIER Credit Card
- Rating
- 4.6
- Downloads
- 1.00M
- Content Rating
- Everyone
PREMIER Credit Card - Screenshots
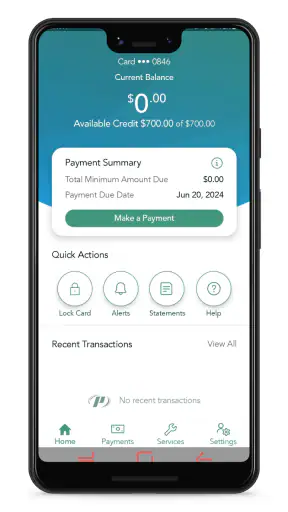
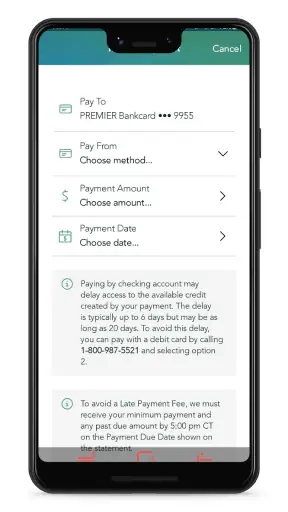
Pros
- Easy access to your account
- balance
- payments
- and transaction history.
- Payment reminders can help reduce the risk of missing your monthly due date.
- In-app card controls may help you monitor and manage account activity.
- Useful support resources are available for common card and payment questions.
- Paperless statements make it easier to review records and reduce mailed paperwork.
Cons
- The app is mainly useful to existing PREMIER cardholders
- not new applicants.
- Some account actions may redirect you to a browser instead of staying in the app.
- Features can vary depending on your card type and account status.
- A mobile app cannot remove the card’s interest charges
- fees
- or credit limits.
- Users may need to contact customer service for complex disputes or account issues.
PREMIER Credit Card - Description
- App Name
- PREMIER Credit Card
- Package Name
- com.firstpremier.mypremiercreditcard.app
- Developer
- PREMIER Bankcard
- Category
- Finance
- Last Updated
- Sep 16, 2019
- Version
- 3.19.5
Managing a credit card from a phone is useful only when the app makes important information easy to find and actions easy to complete. I spent time with PREMIER Credit Card from PREMIER Bankcard to see how well it handles that everyday job, with particular attention to readability, navigation, and the different situations in which someone may need to use it. My overall impression is that it is a focused finance app rather than a broad money-management tool: it is built around keeping an eye on a PREMIER Bankcard account wherever you are.
That focused approach is both its main strength and its main limitation. If your main need is checking your card account, staying aware of activity, and handling routine account management from a mobile device, the app feels appropriately direct. If you want budgeting across several banks, investment tracking, bill planning, or a complete household finance dashboard, you will probably find its scope too narrow. I would think of it as a companion to one specific card relationship, not as a replacement for a full personal-finance service.
How the app feels to use in everyday situations
Readable information and a navigation style that stays focused
The first thing I noticed is that the app’s purpose is immediately understandable. It does not try to surround a card account with unrelated financial products or a long list of planning tools. That matters when I am checking an account quickly, especially before making a purchase or while trying to remember whether a recent payment has appeared. A narrower interface can reduce the amount of searching involved, and this is where the app makes the most sense.
For users who prefer a simple task-based experience, the layout should feel less intimidating than a large banking dashboard. The important question is usually not “What can this entire financial platform do?” but “Where do I go to see what is happening with my card?” Keeping the app tied to PREMIER Bankcard gives the experience a clear boundary. In my view, that is helpful for people who are less comfortable with complicated finance software or who only want to manage one card on their phone.
There is also a practical benefit for people who read information in short sessions. A user may be standing in a shop, sitting on public transport, or checking an account between other tasks. An app designed around a single card is easier to approach in those moments than a service that first asks the user to sort through multiple accounts, categories, and financial products. I found that this focused purpose supports quick orientation, even though it does not provide the wider context of a full budgeting app.
Readability is not only about large text or strong contrast. It is also about whether labels make sense, whether the next action is predictable, and whether the screen asks me to remember too much. A finance app should make me pause before an important action, but it should not make me guess what a button means. PREMIER Credit Card benefits from having a limited set of account-related tasks, because the user is not navigating a large collection of unrelated features.
One useful habit is to open the app at a calm moment and learn where the account overview and recent activity are located, rather than waiting until I am under pressure at a checkout. That small preparation makes the app more accessible for people who need extra time to read or who find rushed navigation difficult. It also reduces the chance of confusing a pending transaction with a completed one when reviewing a purchase quickly.
What the focused design means for different users
For someone who has difficulty processing dense screens, the app’s single-card purpose is a genuine advantage. The user is dealing with one financial relationship instead of combining several accounts in one place. That can make the mental workload lighter. It is especially useful for a person who wants to check the card without opening a larger budgeting system filled with charts and categories that are not relevant to the immediate task.
At the same time, focus should not be mistaken for complete simplicity. Credit-card information still requires careful reading. A person may need to distinguish between a current balance, a transaction, and a payment-related detail. I would not recommend making important financial decisions by glancing at the first number on the screen. The app can help with access to account information, but the user still needs to read the surrounding labels and review the relevant details before acting.
The app is free to install, carries an Everyone content rating, and supports Android devices running version 7.0 or later. That broad device support is helpful for people who keep an older phone rather than upgrading frequently. The current version is 3.19.5, so users should still keep their operating system and app updated when possible, particularly for a finance app where reliability and security habits matter.
Its popularity also suggests that it is not an obscure utility: it has more than a million installs, an average rating of 4.6 from roughly 252,000 ratings, and around 16,000 written reviews. I treat those figures as useful context rather than proof that every user will have the same experience. A person’s phone, vision, motor control, reading needs, and familiarity with mobile banking can change how comfortable the app feels.
Motor, visual, and sensory considerations
Mobile finance tasks can be difficult for reasons that have nothing to do with financial knowledge. A user with limited dexterity may struggle with small touch targets, repeated tapping, or having to hold a phone steady while entering information. A user with low vision may need larger system text or magnification. Someone who is easily distracted by noise may prefer to complete account checks in a quiet place instead of trying to work through a financial task in a busy store.
My practical advice is to use the phone’s own accessibility settings before judging the app. Larger display text, screen magnification, a stronger system contrast setting, or a screen reader may make the experience more manageable, depending on the device. I would test these settings on a non-urgent visit first. Finance is a poor place to experiment while a payment decision is waiting, because an altered layout can change where controls appear or how much content is visible at once.
For motor access, a stylus or a stable surface can help users who find precise tapping tiring. I also prefer completing account checks with both hands free, rather than balancing a phone while carrying shopping bags. This sounds minor, but it is a realistic accessibility issue: a task that is easy at a desk can become awkward when the user is moving, standing, or dealing with another physical demand.
People with cognitive or memory-related difficulties may benefit from a consistent personal routine. For example, I would use the app at the same point in a weekly money check, review recent activity slowly, and avoid switching between several financial apps at the same time. Writing down a question before opening the app can also prevent aimless navigation. The app’s narrow purpose supports this kind of routine better than a service that combines card management with investments, rewards, loans, and household budgeting.
For users who rely on audio or visual assistance, the important question is whether the phone’s built-in tools remain usable across the screens they need. I would not assume that every control will be equally comfortable with every assistive setup. A careful first test is sensible: increase text size, move through the main account areas, select a recent item, and confirm that the information remains understandable. If the experience becomes cramped or confusing, using the card issuer’s other available account-management route may be more practical for that particular user.
Situational access outside the home
The app is most valuable when I need account information away from a computer. Imagine noticing an unfamiliar card transaction while waiting for a bus. A phone-based account tool lets me investigate the activity without returning home to find a laptop. That is a meaningful convenience for users whose mobility, work schedule, or access to a larger screen makes desktop banking inconvenient.
Another realistic situation is shopping with a strict spending limit. I might check the account before completing a purchase, then review the activity later when I have more time. The app helps bring the account into that decision, but I would still avoid rushing through a financial action in a noisy queue. If the screen is hard to read in bright sunlight, or if the user is anxious about holding up other people, waiting for a calmer place may be the more accessible choice.
Travel and commuting create their own barriers. Glare, weak connectivity, low battery, crowded spaces, and privacy concerns can all affect phone banking. A person with hearing loss may not notice an audio cue in a noisy environment, while a person with sensory sensitivity may find a crowded location too distracting for careful financial reading. The app can make mobile access possible, but it cannot remove those physical circumstances.
Privacy is particularly important when using a card app in public. I would avoid displaying account information where another person can easily see the screen, and I would use the phone’s normal lock and privacy habits. Someone who needs a larger display may face a trade-off here: bigger text improves readability but can also make the screen visible from farther away. A quiet, private location is often a better accessibility solution than trying to complete the task in the middle of a crowded space.
The app can also suit people who do not want to manage finances through a desktop browser. Smaller phones may make reading less comfortable, but mobile access can still be preferable for a user who finds a computer mouse difficult or who does not have regular access to a computer. Conversely, a user who needs a very large display, extensive keyboard navigation, or a highly adjustable desktop workspace may be better served by another account-management method.
Where friction and barriers remain
The biggest limitation is the app’s narrow role. It manages a PREMIER Bankcard account, not a complete financial life. I would not choose it as my main tool for comparing spending across multiple cards, building a detailed budget, tracking savings goals, or viewing accounts from different institutions together. A separate budgeting app may be better for those jobs, while the issuer’s own app remains useful for card-specific information.
That separation can create extra work. Someone who uses several financial services may need to move between apps and remember which one contains the current information. For a user with memory difficulties, this can be more frustrating than a unified dashboard. The trade-off is that a dedicated card app may be easier to understand on its own, while a broader service offers more context but usually demands more setup and navigation.
Small-screen finance work also has an unavoidable risk of misreading. A user who enlarges text may need to scroll more, while a user who keeps more content visible may find the text too small. I recommend checking one item at a time and confirming the meaning of each label before making a payment-related decision. This is not a criticism unique to one screen; it is a general challenge of managing detailed financial information on a phone, and the app’s focused design does not eliminate it.
Another potential barrier is dependence on the phone itself. A dead battery, damaged screen, forgotten device passcode, or unavailable connection can interrupt access at the exact moment it is needed. People who rely heavily on mobile account management should keep an alternative way to contact or manage their card available. I would not make the app my only plan for urgent account problems.
Users who need highly customized accessibility controls should approach it with realistic expectations. The app may work well with the phone’s standard tools, but that does not mean every individual need will be covered equally. A person who requires a particular navigation pattern, extensive keyboard operation, or unusually high magnification should test the exact tasks they perform most often before depending on the app.
Who should use it, and who should choose something else?
I would recommend PREMIER Credit Card to an existing PREMIER Bankcard customer who wants a direct mobile way to stay connected to the card account. It is especially suitable for someone who values a focused interface, checks account activity regularly, and prefers using a phone instead of a desktop. It can also be a sensible choice for users with older Android phones, since its minimum operating-system requirement is Android 7.0 or later.
I would be more cautious if the user has several cards and expects one app to organize everything. In that case, a broader personal-finance app may offer better overview and comparison, even if it is more complex. I would also suggest another route for someone who needs a large monitor, advanced keyboard control, or a very specific assistive workflow. The right choice depends less on the app’s general reputation than on whether its account tasks match the user’s actual access needs.
The developer, PREMIER Bankcard, has kept the product centered on its own card relationship. That is reassuring in terms of purpose: I know what the app is for when I open it. But it also means I should not expect the kind of cross-account analysis found in general finance tools. The comparison is straightforward: this app favors issuer-specific convenience, while a budgeting alternative favors a wider financial picture.
My inclusive verdict after using it
PREMIER Credit Card is a practical, focused finance app that can make card management easier to approach on a phone. Its strongest accessibility quality is not a flashy feature; it is the decision to concentrate on one card account instead of turning the experience into a full financial command center. That can reduce clutter, shorten the path to common information, and help users who prefer a limited number of clear tasks.
Still, I would not call it universally accessible based on its purpose alone. People with visual, motor, cognitive, or sensory needs should test the app with their phone’s accessibility settings and with the exact account actions they expect to perform. Public use, small screens, privacy, connectivity, and dependence on one device remain real barriers. These issues do not make the app unsuitable, but they do make preparation important.
With a 4.6 average and a large user base, it is clearly a well-established option for customers of PREMIER Bankcard. I see it as best for routine card awareness rather than broad financial planning. If that is the job you need done, the free app is worth trying. If you want one place for every account or require a highly specialized access setup, I would pair it with another tool or choose a service designed around those wider needs instead.
My final recommendation is simple: use it as a dedicated card companion, not as your entire financial system. Set up your preferred phone display settings, learn the main navigation when you are not rushed, and review sensitive information in a private, well-lit place. Those habits make the focused design work better for more people and help turn a convenient mobile account tool into one that is genuinely usable in everyday life.
FAQ
What is the PREMIER Credit Card app used for?
The PREMIER Credit Card app is designed to help cardholders manage their account from an Android or iOS device. After signing in, you can typically review your current balance, available credit, recent transactions, payment due date, minimum payment, and account notices. It is mainly a convenient account-management tool rather than a shopping or banking app for people without a PREMIER card.
How do I log in to the PREMIER Credit Card app?
To use the app, you generally need an existing PREMIER Credit Card online account. During setup, the application may ask you to enter your username and password, and it can require additional identity verification for security. If you have not registered for online access, you may need to complete enrollment first. Users should download the official app and avoid entering credentials into unofficial copies or suspicious links.
Can I pay my PREMIER Credit Card bill through the app?
Yes, the app is intended to make account payments more convenient for eligible cardholders. You can usually select a payment amount, choose an available bank account, and schedule a one-time payment or manage payment settings, depending on the features currently offered. Before confirming, carefully check the payment date and amount, since processing times and available options may vary.
Does the PREMIER Credit Card app show transactions and available credit?
The app normally provides a quick view of important account information, including posted transactions, current balance, available credit, minimum payment, and payment due date. This makes it useful for monitoring spending and checking whether a payment has been applied. However, recent purchases may not appear immediately, and pending transactions or updates can take time to be reflected.
Is the PREMIER Credit Card app free and safe to use?
Downloading and using the official PREMIER Credit Card app is generally free, although your credit card account may still have fees, interest, or other charges described in its agreement. Security features can include encrypted connections, password protection, and identity verification, but users should still protect their login details, enable device security, update the app, and install it only from the official Google Play Store or Apple App Store.


